Working capital for practices waiting on insurance
Patients are seen today. Insurance pays in weeks or months. A line of credit keeps payroll and supplies covered while claims are processed.
- Cover staff payroll during reimbursement delays
- Buy equipment and supplies
- Fund a new provider or location
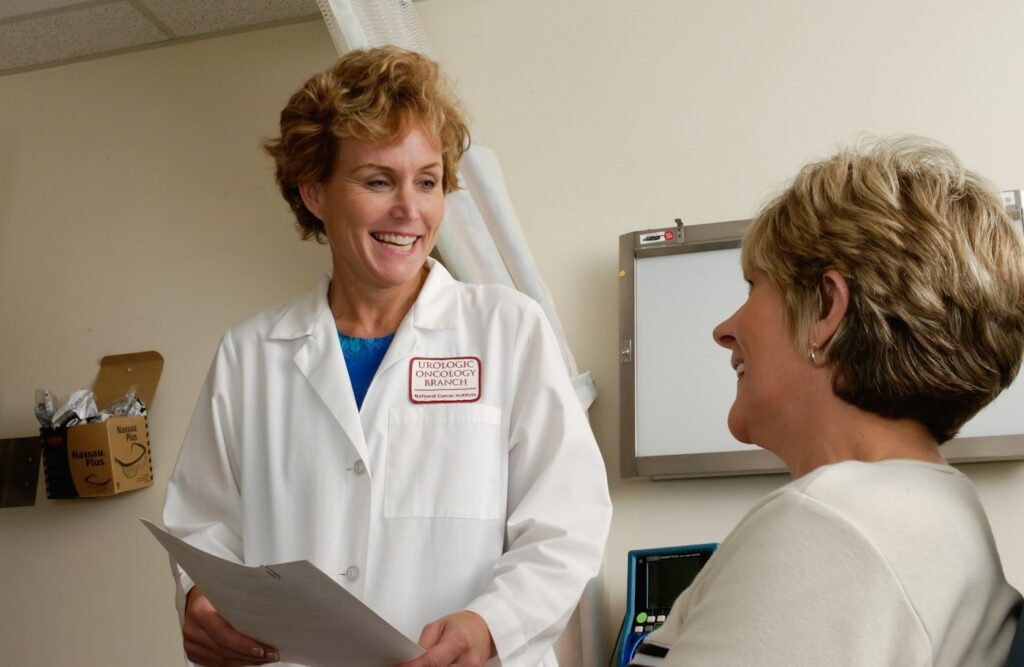
Reimbursement delays shouldn’t slow down care
Medical practices often have healthy books and tight bank accounts at the same time. Claims take time, denials have to be worked, and payer mix can change what lands each month.
Physician groups, urgent care centers, chiropractors, physical therapists and other providers use a Flex Credit Capital line to keep operations steady while receivables catch up.
Common uses
- Covering payroll for nurses and front-desk staff
- Buying or upgrading medical equipment
- Bringing on a new provider
- Renovating exam rooms or opening a second office
The basics we look for
If your business checks these boxes, it’s worth a few minutes to apply.
We look at how your business is actually doing, mostly through your recent bank statements. Your credit score matters less here than it does at a bank.
- Time in business6 months or more
- Monthly revenue$15,000 or more
- Business bank accountRecent statements
- LocationU.S.-based business
- CollateralNot required
Questions from medical practice owners
Do insurance receivables count?
We look mainly at your actual deposits and bank statements, which reflect the reimbursements you receive.
Can specialty practices apply?
Yes. We work with a wide range of providers.
Will you contact my patients or payers?
No. A line of credit doesn’t involve your patients or payers.
See what your business qualifies for
Tell us what you need the money for and how much. A funding advisor will follow up with real numbers, usually the same day.