Funding for restaurants that can’t afford a slow week
Margins are thin and the walk-in doesn’t care that it’s been a slow month. A line of credit keeps the kitchen running and the staff paid.
- Cover food costs and payroll
- Fix equipment the day it breaks
- Get ready for patio season and holidays
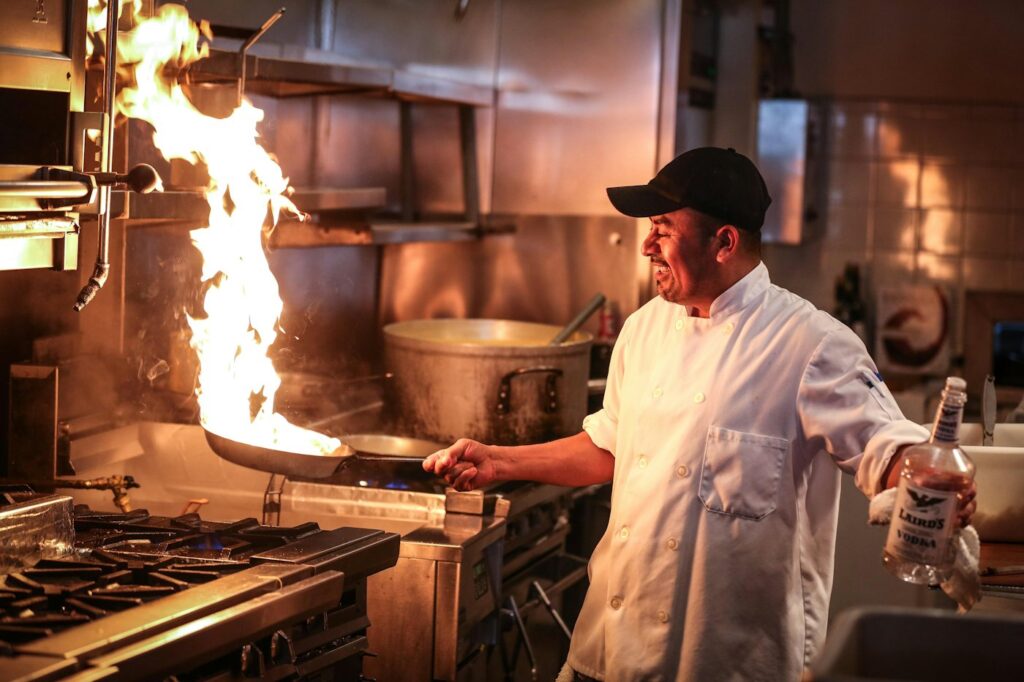
Restaurants run on tight timing
Food costs move every week, staff get paid every week, and one broken cooler can wipe out a weekend’s profit. Most restaurant owners don’t need a huge loan. They need money they can reach for when timing gets tight.
Restaurants, cafes, bars, food trucks and caterers use a Flex Credit Capital line to smooth out the swings and keep the doors open through slow stretches.
Common uses
- Covering payroll during a slow week or month
- Repairing or replacing kitchen equipment
- Stocking up before holidays and big events
- Small remodels, patio builds and new menus
The basics we look for
If your business checks these boxes, it’s worth a few minutes to apply.
We look at how your business is actually doing, mostly through your recent bank statements. Your credit score matters less here than it does at a bank.
- Time in business6 months or more
- Monthly revenue$15,000 or more
- Business bank accountRecent statements
- LocationU.S.-based business
- CollateralNot required
Questions from restaurant owners
Do you fund new restaurants?
We generally need at least 6 months in business with steady revenue in your bank account.
Do card sales count toward my revenue?
Yes. We look at the deposits into your business bank account, which includes your card processing deposits.
Can I use it to open a second location?
Yes, expansion is a common use. Talk to your advisor about the amount you’ll need.
See what your business qualifies for
Tell us what you need the money for and how much. A funding advisor will follow up with real numbers, usually the same day.